High-Stakes Israeli Election Threatens Middle East Trade Corridors and Energy Stability
As Israel approaches a critical parliamentary election, the formation of its next coalition government carries sweeping implications for Eastern Mediterranean gas assets, regional security pacts, and vital trade conduits.
Geopolitical & Core Developments
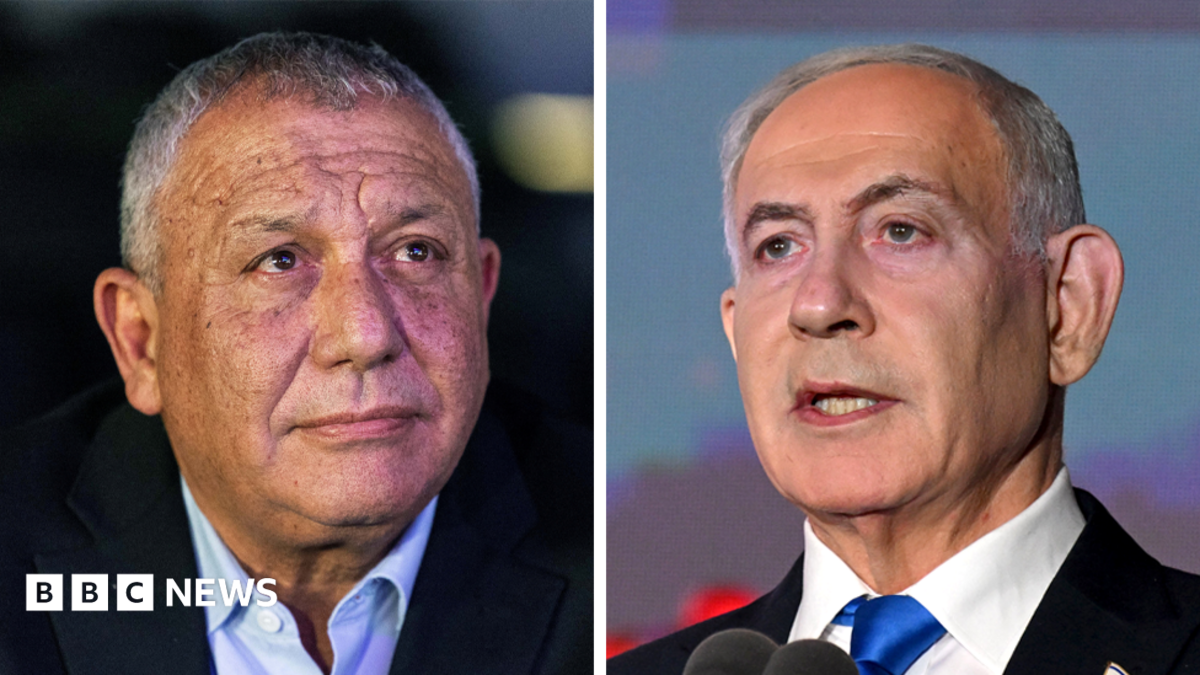
Israel's parliamentary electoral framework, operating under a pure proportional representation model across a single nationwide constituency, is once again poised to reshape the geopolitical equilibrium of the Middle East. Voters cast ballots for party lists rather than individual candidates, with any faction passing the 3.25 percent threshold securing seats in the 120-seat Knesset. Because no single party has ever achieved an outright 61-seat majority in the country's modern history, governance hinges entirely on coalition dynamics. The current contest pits incumbent Prime Minister Benjamin Netanyahu's right-wing Likud and allied religious-nationalist factions against a disparate bloc of centrist and liberal contenders, including Benny Gantz's National Unity and Yair Lapid's Yesh Atid.
The strategic stakes of this ballot extend far beyond domestic judicial and social policy. Following months of direct military confrontation across Gaza, southern Lebanon, and intermittent exchanges with Iran, the ideological posture of the emerging governing coalition will dictate the parameters of regional engagement. A hardline coalition guarantees a protracted, militarized posture across Israel's northern and southern frontiers, whereas a centrist-led administration could pursue conditional de-escalation frameworks backed by Western allies. With domestic public sentiment highly polarized, the timeline toward forming a stable government remains volatile, raising the prospect of protracted horse-trading that leaves strategic foreign policy in a state of suspended animation.
Global Trade & Economic Ripples
The composition of the next Knesset has immediate ramifications for Eastern Mediterranean energy infrastructure and multinational maritime commerce. Israel has evolved into a strategic gas exporter via the offshore Leviathan and Tamar fields, delivering essential natural gas to Egypt and Jordan while facilitating indirect LNG transshipments to European markets seeking alternatives to Russian hydrocarbons. Heightened domestic instability or the appointment of ministers favoring unilateral military expansion threatens offshore platforms, escalating war-risk insurance premiums for commercial vessels transiting the Levant Basin.
Furthermore, cross-border commercial frameworks hang in the balance. The progress of the India-Middle East-Europe Economic Corridor (IMEC)—designed to link South Asia to Europe via rail and shipping routes through the United Arab Emirates, Saudi Arabia, and Israel—remains fundamentally paused. Commercial capital expenditure across the regional tech and logistics sectors has decelerated as international institutional investors hedge against the Israeli shekel and broader Middle Eastern sovereign debt. Sustained disruption across regional chokepoints, particularly ongoing threats along Red Sea approaches linked to broader anti-Israel proxy activity, continues to elevate freight rates and divert container tonnage around Africa's Cape of Good Hope.
Related Intelligence: Russia Positions as Potential Broker in Stalled US-Iran Nuclear Negotiations
International Reactions & Diplomatic Stances
Global stakeholders have adopted a posture of guarded vigilance. The United States administration has reiterated its ironclad defense commitments while privately communicating concerns regarding the inclusion of ultra-nationalist elements in any prospective cabinet, warning that such alignments could derail broader Saudi-Israeli normalization negotiations. European Union foreign policy officials have emphasized that future bilateral trade agreements and research partnerships remain tethered to adherence to international humanitarian law and tangible progress toward a two-state framework.
Conversely, regional signatories to the Abraham Accords—most notably the UAE and Bahrain—maintain a pragmatic yet cautious engagement. Commercial ties remain functional, but high-level diplomatic visibility has been scaled back to mitigate domestic backlash. In Washington and Brussels, international risk analysts note that a fragmented Israeli parliament unable to project coherent security guarantees will exacerbate diplomatic paralysis, limiting multilateral efforts to stabilize critical maritime corridors.
Strategic Outlook & Future Scenarios
The immediate trajectory points to weeks of contentious negotiations post-election, with three distinct scenarios facing global markets. A consolidated right-wing alliance would prioritize territorial entrenchment, likely deepening friction with Western capitals and permanently freezing normalization talks with Riyadh. Alternatively, a broad national-unity coalition would seek immediate re-alignment with Washington, potentially unlocking stalled energy infrastructure initiatives and easing sovereign credit pressures.
The most disruptive scenario remains a hung parliament, which would propel the nation into repeated interim governance cycles, paralyzing long-term economic planning and delaying crucial multilateral agreements on Mediterranean resource sharing. As the electorate heads to the polls, international commodity desks and diplomatic corps are preparing for an extended period of heightened volatility across Mediterranean energy hubs and global shipping lanes.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.