Three Years After October 7: Israel's Political Shift and Global Market Impacts
Three years following the October 7 attacks, the resulting trauma continues to reshape Israeli domestic politics, regional military engagements, and global commodity markets.
Geopolitical & Core Developments
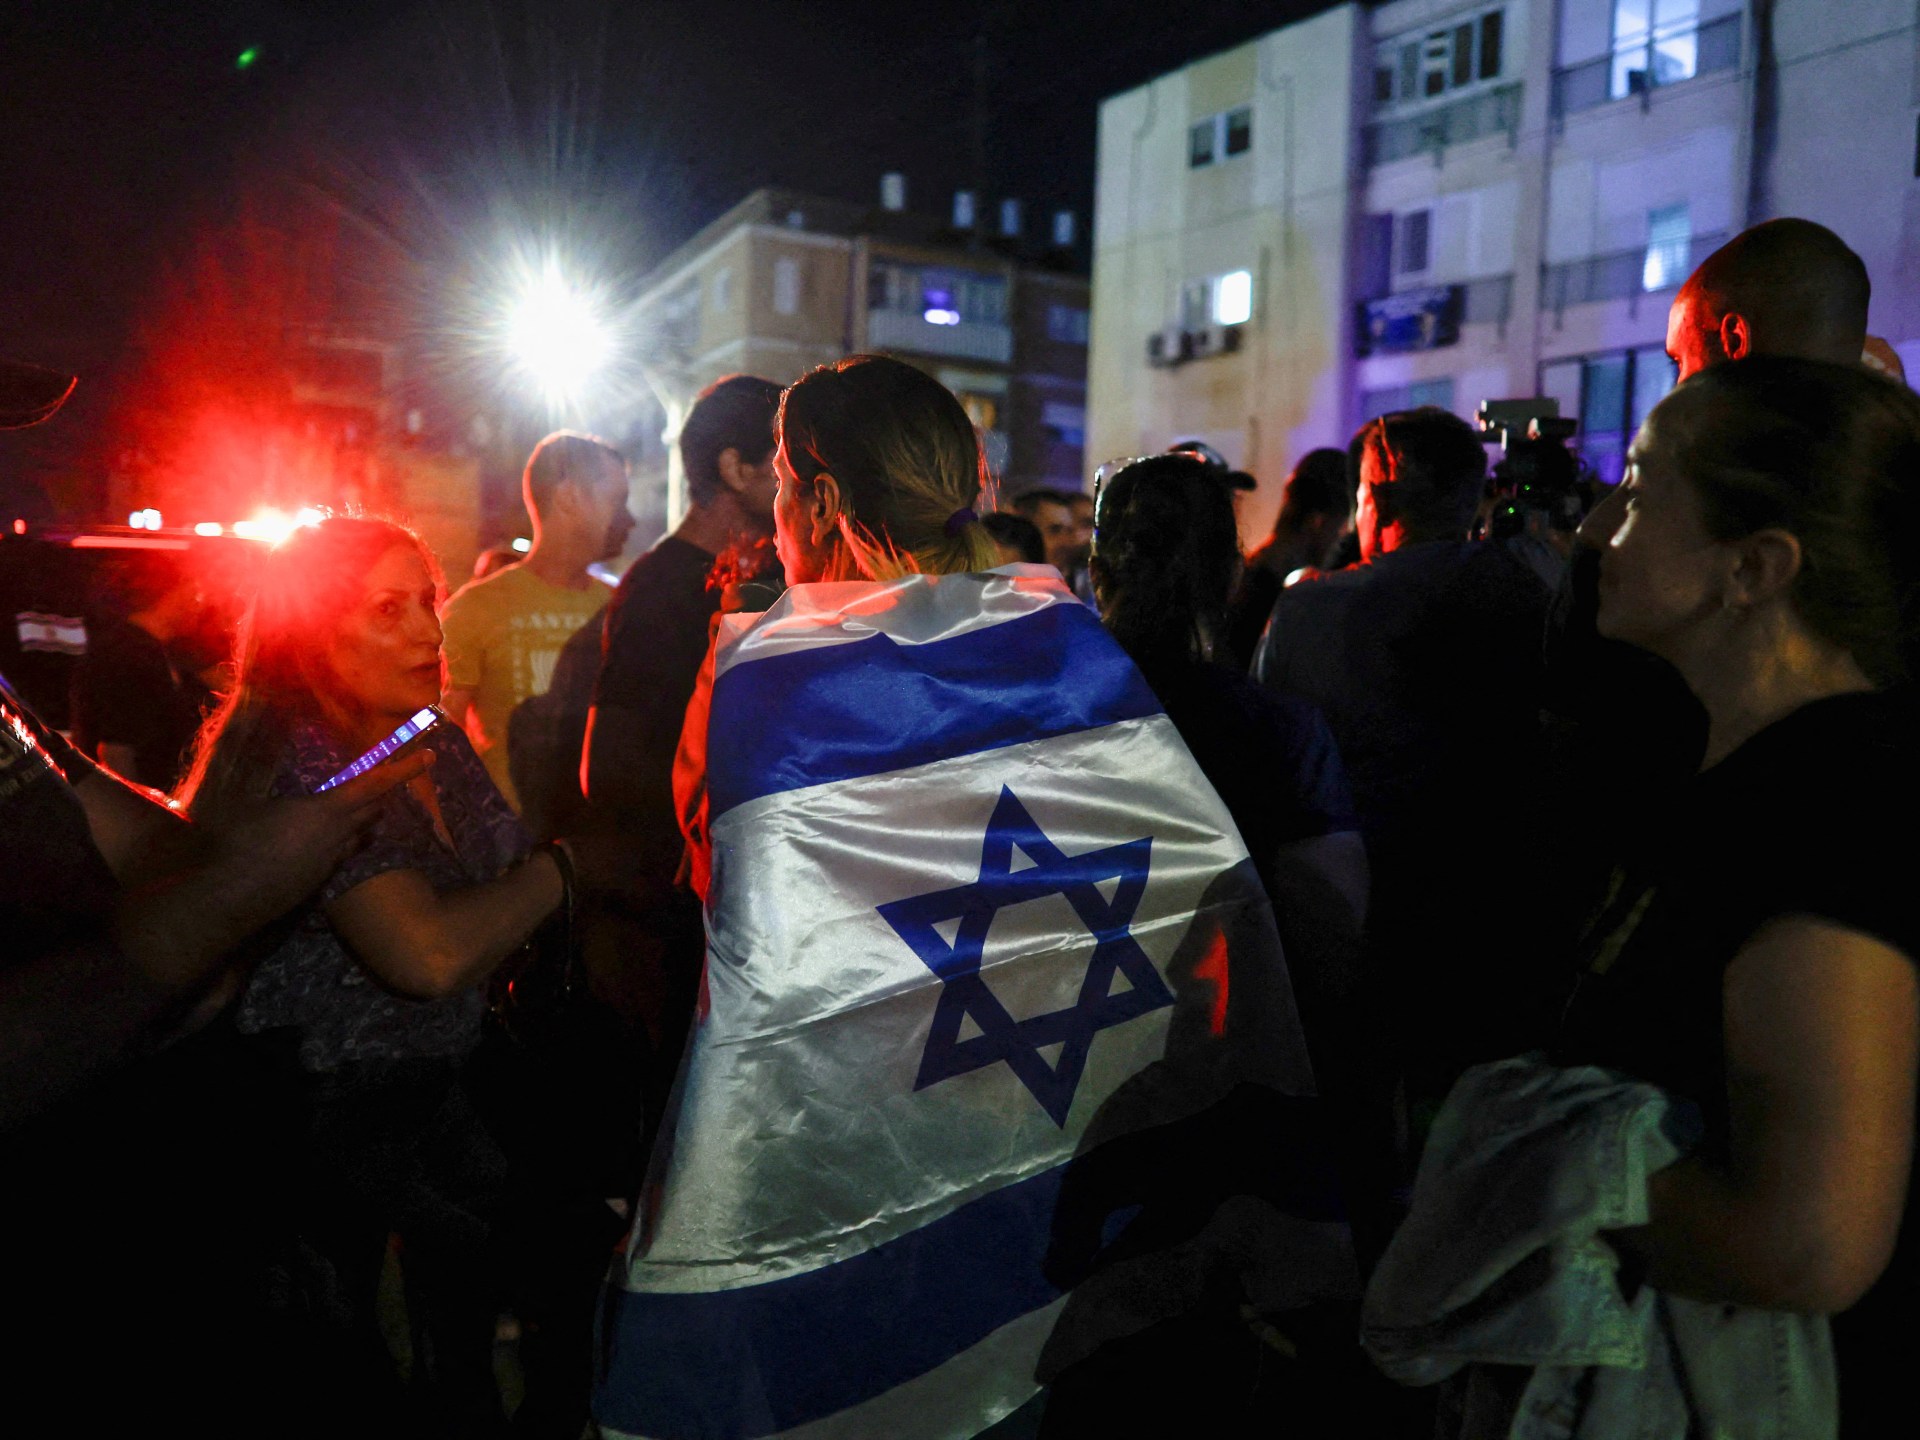
Three years after the devastating events of October 7, the geopolitical architecture of the Middle East has undergone a profound and irreversible transformation. The initial security shock fractured Israel's internal consensus, accelerating a decisive lurch toward the far-right within the current governing coalition. This political pivot has not only hardened military postures across multiple active fronts—spanning Gaza, Lebanon, and strategic deterrent operations against regional proxies—but has also redefined civil-military relations inside the state. State actors and diplomatic channels have found traditional frameworks of deterrence obsolete, replaced by a prolonged state of multi-front attrition. The strategic stakes have escalated far beyond immediate border security, drawing in major global powers and altering long-standing alliances across the Mediterranean and the Gulf. Regional diplomacy remains paralyzed as territorial ambitions, hostage crises, and questions of day-after governance in besieged enclaves supersede any immediate prospect of a durable peace settlement.
[Global Trade](/news/west-bank-dispossession-accelerates-global-trade-security-risks) & Economic Ripples
The protracted nature of the conflict has sent persistent shockwaves through global trade networks, energy markets, and supply chains. Maritime security in the Red Sea and the Bab el-Mandeb strait remains severely compromised due to persistent asymmetric threats targeting commercial shipping. Consequently, global logistics firms have been forced to reroute vessels around the Cape of Good Hope, adding weeks to transit times between Asian manufacturing hubs and European consumer markets while inflating freight rates and marine insurance premiums. In the energy sector, heightened anxiety over potential escalations involving major regional producers has introduced persistent volatility into crude oil and liquefied natural gas benchmarks. While immediate physical supply disruptions have been partially mitigated by spare capacity, commodity traders continue to price in elevated geopolitical risk premiums, impacting inflation trajectories and currency values across import-reliant economies.
Related Intelligence: West Bank Dispossession Accelerates Amid Global Trade and Security Risks
International Reactions & Diplomatic Stances
The international community remains deeply fractured in its response to the ongoing crisis. The United Nations and various multilateral humanitarian agencies have repeatedly warned of catastrophic civilian tolls and systemic violations of international humanitarian law, calling for immediate, unhindered aid access and permanent ceasefires. However, diplomatic polarization within the UN Security Council has repeatedly stalled binding resolutions. Western governments face delicate domestic balancing acts, torn between historic commitments to Israeli security and mounting public pressure to curb military operations and address humanitarian devastation. Meanwhile, emerging economies and Global South actors have increasingly utilized the crisis to critique perceived double standards in international law, further accelerating the fragmentation of multilateral governance and deepening geopolitical realignments.
Strategic Outlook & Future Scenarios
Looking toward the medium term, the strategic outlook for Israel and the broader region remains highly volatile, characterized by the risk of miscalculation and wider state-on-state escalation. Upcoming international summits and emergency diplomatic conferences are unlikely to yield breakthrough frameworks while domestic political survival dictates the agendas of key regional leaders. Economic analysts anticipate that prolonged defense spending will strain Israel's sovereign credit rating and fiscal reserves, even as the nation's high-tech and defense sectors experience localized booms driven by wartime innovation. Sanction regimes, export controls on dual-use technologies, and shifting foreign direct investment patterns will continue to punish regional economies. Ultimately, the trajectory set in motion three years ago points toward a protracted era of fragmented security architectures, persistent supply chain vulnerability, and heightened geopolitical risk for global commerce.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.