India Set to Surpass Japan as Fourth-Largest Economy by 2027
The International Monetary Fund projects India will surpass Japan as the world's fourth-largest economy by 2027, driven by sustained domestic expansion while Japan contends with demographic and currency pressures.
The Core Development
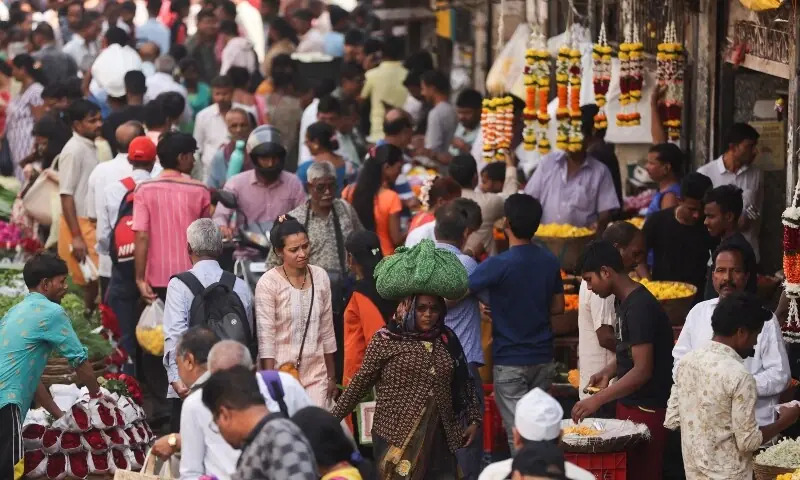
The International Monetary Fund (IMF) has updated its medium-term global economic outlook, projecting that India will overtake Japan to become the world's fourth-largest economy by nominal gross domestic product (GDP) in 2027. According to data released in Washington, India’s economic output is expected to expand to $4.52 trillion by the reference year. The revision reflects diverging macroeconomic trajectories across major Asian economies.
While Japan is slated to retain the fourth position through the current fiscal cycle, structural headwinds—including severe domestic currency depreciation against the US dollar and an aging, shrinking workforce—continue to compress its nominal dollar-denominated output. The multilateral lender’s projections indicate that by 2027, Japan will slip to sixth place globally, falling behind both India and the United Kingdom. In tandem with these shifts, the IMF raised its growth forecast for the Indian economy, anticipating sustained expansion near 7.0 percent, underpinned by robust domestic consumption and accelerated public infrastructure spending.
Commercial & Economic Implications
For Pakistan's commercial landscape, the continued expansion of a major neighbouring economy introduces pronounced regional supply chain and trade imbalances. While direct formal bilateral trade between Islamabad and New Delhi remains heavily curtailed due to persistent geopolitical friction, the shift in regional economic weight alters the dynamics of multilateral trade corridors, third-party transshipments via Gulf hubs, and regional commodity pricing.
Domestic wholesale distributors and retail operators in Pakistan face indirect competition in securing capital goods, raw materials, and agricultural commodities on global markets. India's rising purchasing power and manufacturing footprint enhance its absorption capacity for raw industrial inputs, including crude oil, industrial metals, and petrochemicals. This concentration of regional demand often exerts upward pressure on landing costs for smaller South Asian importers. Conversely, structural expansion across borders highlights the urgency for Pakistan’s industrial sector to overhaul logistics, rationalize energy tariffs, and upgrade port operations to prevent wider disparities in regional cost competitiveness.
Related Intelligence: Pakistan Placed Second-Worst in South Asia on Global Hunger Index
Stakeholder Perspectives & Market Reactions
Regional market analysts and domestic industrial bodies have observed the IMF findings with a focus on regional integration and structural reform. Financial analysts point out that nominal GDP rankings, while indicative of aggregate economic mass, do not fully capture underlying vulnerabilities such as per-capita income disparities, underemployment, and fiscal deficits that continue to challenge developing South Asian markets.
Within Pakistan, representatives from trade associations and export chambers note that prolonged trade restrictions deprive local manufacturers of potential proximity advantages in low-cost intermediate inputs, including pharmaceutical APIs, textile dyes, and agricultural equipment. Economists in Karachi emphasize that the divergence between India's sustained trajectory above 6 to 7 percent and Pakistan's cyclical balance-of-payments constraints demonstrates the necessity of structural deregulation, export diversification, and fiscal discipline to restore domestic macroeconomic stability.
Forward Outlook & Key Watchpoints
The IMF’s timeline toward 2027 hinges on several volatile macroeconomic variables. A critical indicator will be the trajectory of global monetary policy, particularly the interest rate spread between the US Federal Reserve and the Bank of Japan, which directly governs the valuation of the yen and consequently nominal dollar GDP calculations.
Furthermore, market observers will monitor how global trade realignments, geopolitical tensions, and raw commodity price swings affect emerging market expansion. In South Asia, the immediate watchpoint remains whether broader multilateral platforms or bilateral mechanisms will eventually permit normalized transit trade and commercial exchanges, or whether structural divergence will further isolate non-diversified regional economies from broader continental supply networks.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.