US Labor Market Cools Sharply as September Job Growth Slows to 29,000
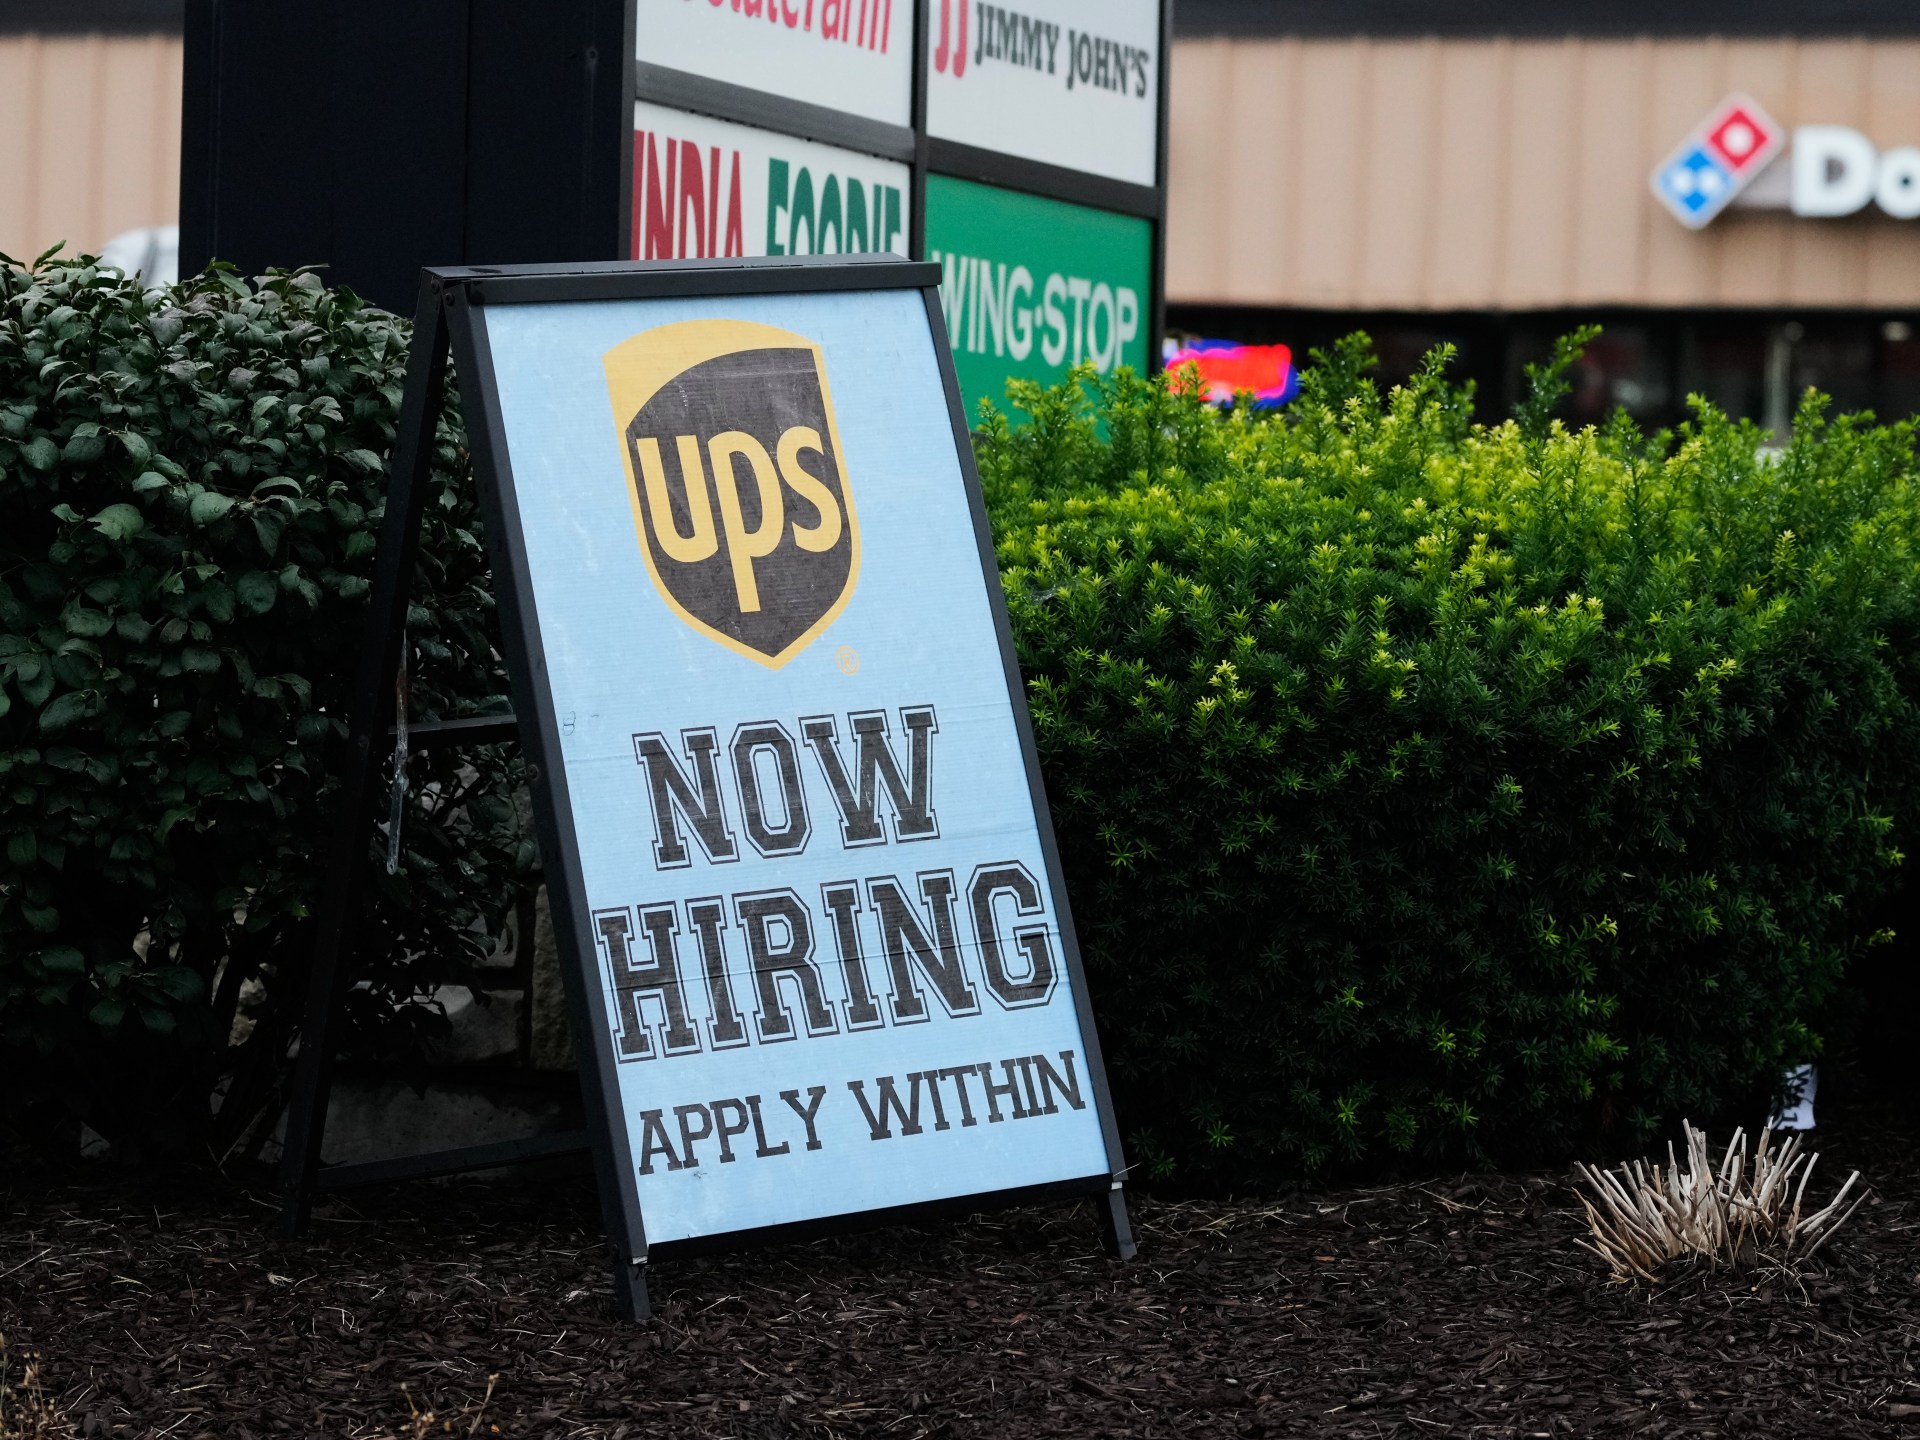
US job growth slowed significantly in September with the addition of only 29,000 jobs, while the unemployment rate edged up to 4.2 percent, signaling mounting economic headwinds ahead of the midterm elections.
Geopolitical & Core Developments
The United States labor market experienced a dramatic deceleration in September, according to data released by the Department of Labor, with the economy adding a meager 29,000 jobs. Concurrently, the national unemployment rate crept upward to 4.2 percent. This sharp cooling of domestic employment dynamics arrives at a precarious political juncture, casting long shadows over the macroeconomic landscape as the nation approaches high-stakes midterm elections. Policymakers and political strategists alike are closely monitoring these metrics, as sustained labor market softness traditionally shifts voter sentiment and alters the legislative leverage of the incumbent administration.
The deceleration in hiring reflects a confluence of prolonged high interest rates, subdued business confidence, and structural adjustments across key industrial sectors. For months, the Federal Reserve has maintained restrictive monetary stances to anchor inflationary pressures. However, the transmission mechanism of these policies is now palpably manifesting in corporate hiring freezes and selective workforce reductions. State actors and international observers note that the resilience previously exhibited by the American consumer and labor market is encountering formidable resistance, prompting intense domestic debate regarding fiscal stimulus and regulatory interventions.
Global Trade & Economic Ripples
As the world's largest economy, shifts in US macroeconomic indicators inevitably trigger cascading effects across global commodity markets, international trade flows, and foreign exchange valuations. The lackluster employment report immediately reverberated through currency markets, exerting downward pressure on the US dollar as investors recalibrate expectations for upcoming Federal Reserve rate cuts. A softer dollar typically provides temporary relief for emerging market economies burdened by dollar-denominated debt, while simultaneously influencing global commodity pricing structures, including crude oil, industrial metals, and agricultural futures.
International supply chains and energy markets are also reacting to the prospect of moderated US demand. Reduced industrial activity and slowing domestic consumption signal potential contractions in import volumes, affecting major trading partners across Asia, Europe, and Latin America. Shipping lanes and freight forwarders are bracing for potential volume adjustments as multinational corporations review inventory strategies in light of shifting macroeconomic forecasts. Commodity traders are closely evaluating whether this domestic economic deceleration will curtail global energy consumption, potentially depressing Brent and WTI crude benchmarks in the near term.
Related Intelligence: Yemen Food Crisis Deepens as Conflict Severely Disrupts Global Supply Chains
International Reactions & Diplomatic Stances
Multilateral institutions and international financial authorities have responded to the US employment figures with guarded vigilance. Representatives from the International Monetary Fund and the World Bank emphasized the interconnectedness of global growth, noting that any prolonged stagnation in the United States could dampen global economic expansion. European central bankers and Asian trade ministers are reassessing their own monetary policy trajectories, factoring in the likelihood of a more accommodative Federal Reserve posture in the coming quarters.
Market analysts and institutional economists have offered varied interpretations of the September data. While some view the slowdown as a necessary and orderly normalization following years of overheated expansion, others warn of downside risks pointing toward a potential economic landing. Foreign diplomatic missions in Washington are advising their respective capitals to prepare for heightened political volatility as domestic economic debates intensify ahead of the electoral cycle, potentially influencing international trade negotiations and bilateral economic pacts.
Strategic Outlook & Future Scenarios
Looking ahead, the trajectory of the US economy will hinge heavily on upcoming monetary policy decisions and the legislative outcomes of the midterm elections. Financial markets have sharply increased their bets on aggressive interest rate reductions by the central bank to forestall further labor market deterioration. Upcoming diplomatic summits, including gatherings of G20 finance ministers, will likely feature intensive consultations regarding global macroeconomic coordination and currency stability.
Geopolitical risk assessments for the fourth quarter now incorporate heightened domestic political uncertainty in Washington. Should labor market conditions deteriorate further, policymakers may face intense pressure to enact targeted stimulus measures, which could alter fiscal deficit projections and impact global sovereign debt markets. Stakeholders across international trade and commodity sectors must maintain agile operational strategies to navigate potential volatility in currency values, trade barriers, and global demand indices over the medium term.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.