US Inflation Surge Triggers Federal Reserve Rate Hike Fears Before Midterms
Resurgent US inflation figures ahead of crucial midterm elections have heightened expectations of aggressive Federal Reserve interest rate hikes, destabilizing global financial markets and commodity flows.
Geopolitical & Core Developments
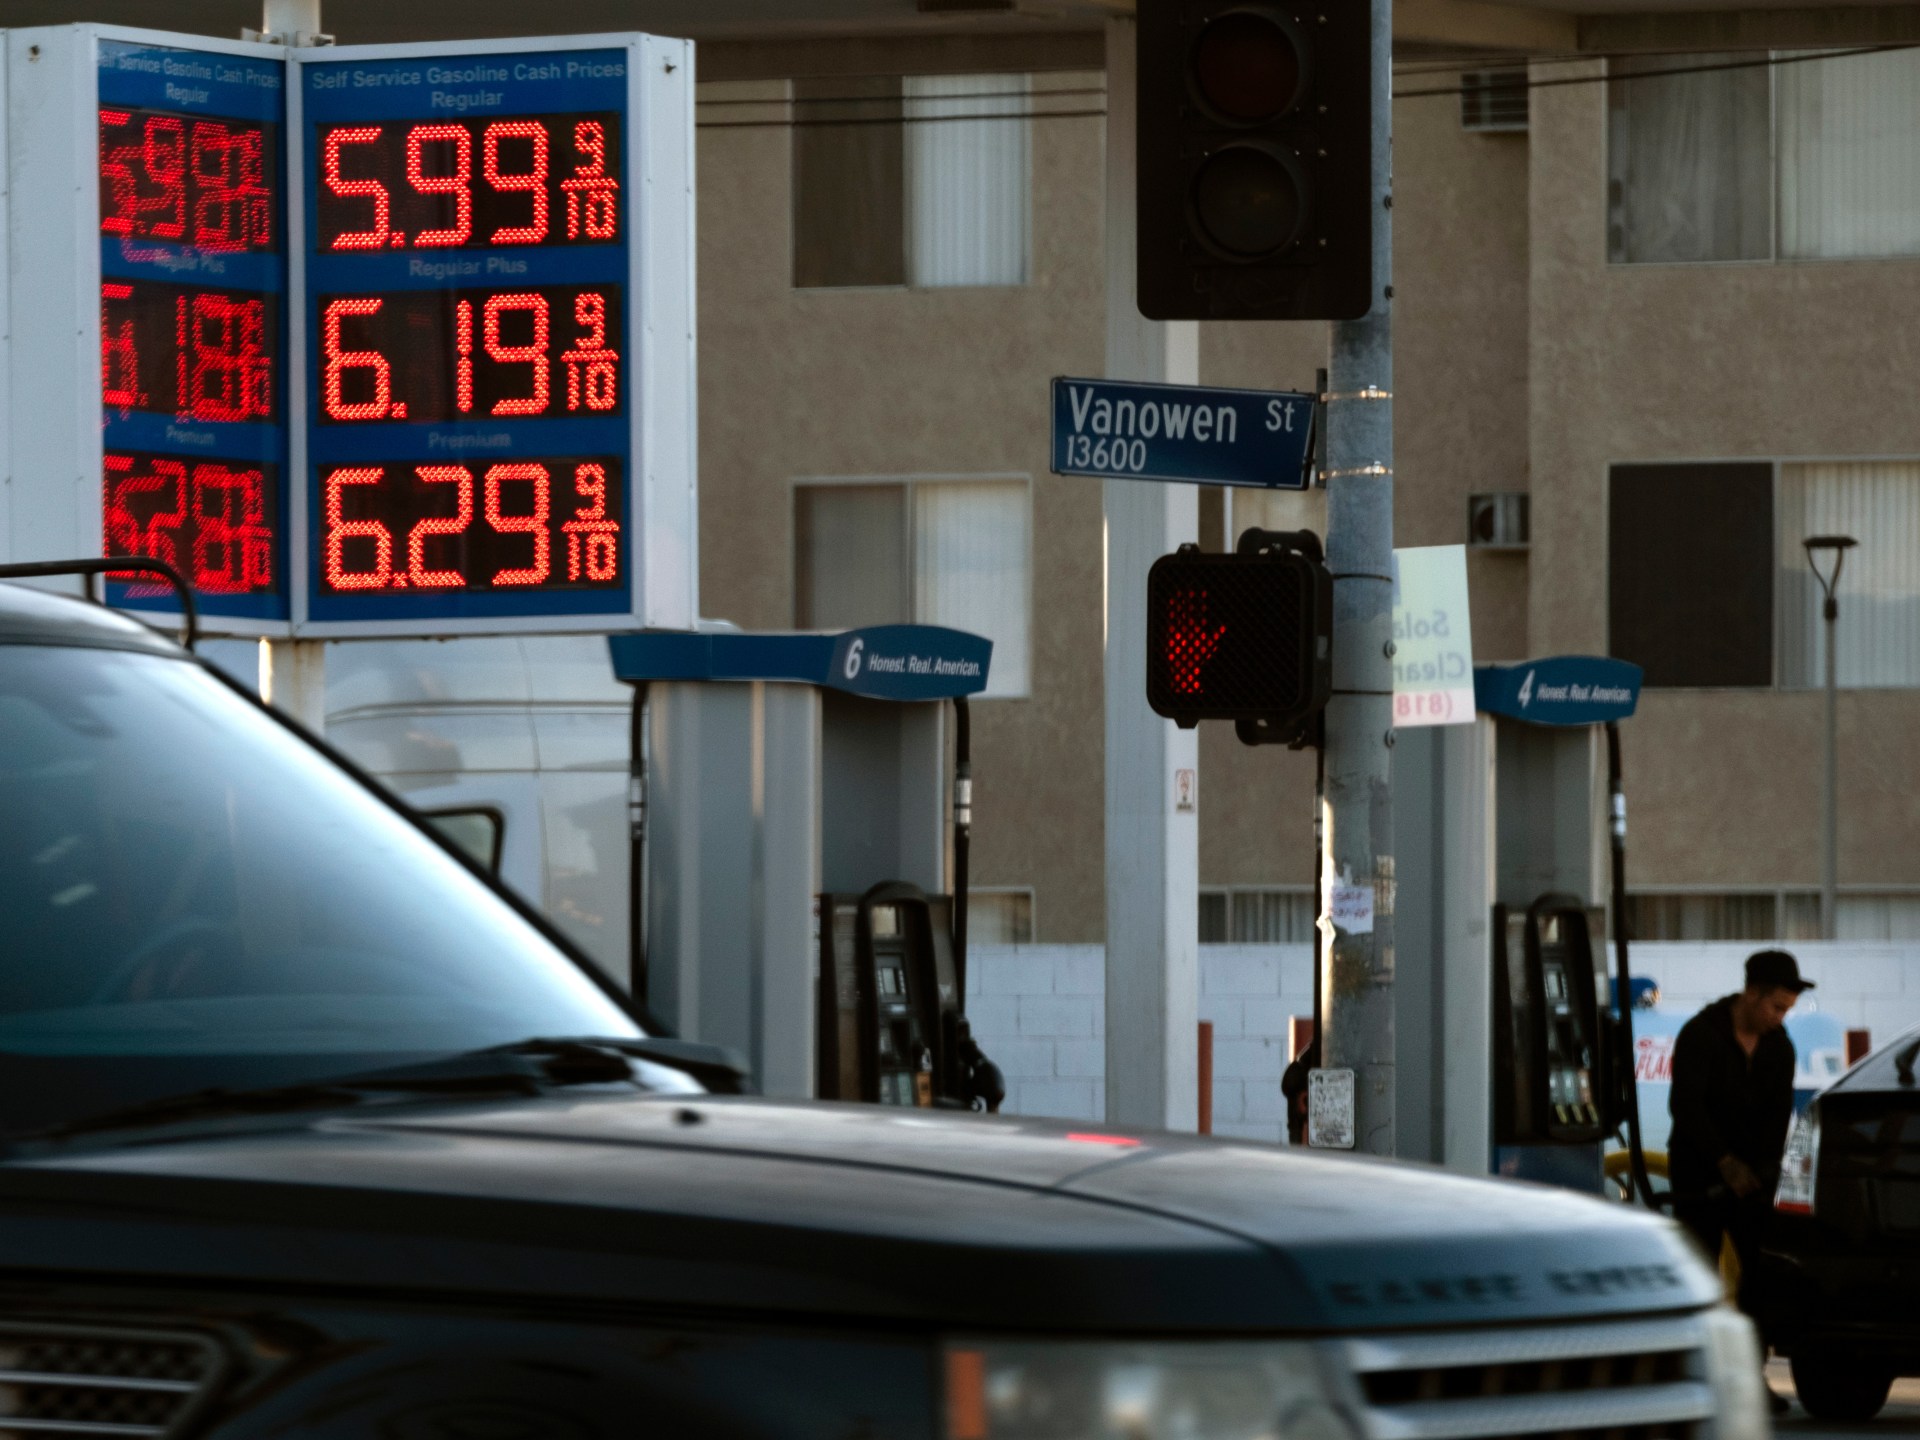
The United States economic landscape faces intensified scrutiny as core inflation metrics registered sharper-than-expected gains immediately preceding the pivotal US midterm elections. The consumer price index data revealed widespread price pressures across essential sectors, including shelter, food, and energy services, confounding previous forecasts of a near-term plateau. For the Biden administration and congressional leadership, the economic data presents acute political vulnerabilities, transforming domestic monetary debates into a critical geopolitical factor.
The persistence of elevated price levels has placed the US Federal Reserve in an increasingly rigid policy corridor. Fed officials face compounding pressure to execute sustained 75-basis-point interest rate adjustments, prioritizing price stability even at the expense of domestic economic contraction. The macroeconomic divergence between Washington's policy trajectory and those of other advanced democracies has deepened domestic division while testing the durability of cross-border monetary coordination.
[Global Trade](/news/yemen-war-scenarios-houthi-red-sea-trade-impact) & Economic Ripples
The immediate consequence of accelerated US policy tightening has been the aggressive appreciation of the US dollar against major reserve and developing currencies. As the greenback reaches multi-decade highs against the euro, British pound, and Japanese yen, international trade denominated in dollars faces acute friction. Emerging market economies are particularly exposed, confronting sovereign debt service escalations and depleted foreign currency reserves necessary to finance vital imports.
Global commodity pricing has responded with pronounced volatility. Crude oil, industrial metals, and agricultural benchmarks, typically priced in dollars, face double-edged pressures: higher nominal local currency import costs depress physical demand in import-dependent Asian and European economies, while aggressive capital flight toward dollar-backed safe-haven assets dampens institutional investment in productive physical supply chains. Shipping rates and cross-border trade financing have simultaneously tightened, as international commercial banks recalibrate counterparty risk amid higher borrowing costs.
Related Intelligence: Yemen War at Crossroads as Escalation Threatens Global Trade Corridors
International Reactions & Diplomatic Stances
Multilateral bodies have voiced rising apprehension regarding the international ramifications of unilateral monetary tightening. Officials at the International Monetary Fund and the United Nations Conference on Trade and Development have cautioned that synchronized policy tightening in advanced economies risks precipitating a synchronized global recession, disproportionately damaging low-income sovereign borrowers.
In Europe and Asia, central bank governors have signaled growing unease over imported inflation stemming from currency depreciation against the dollar. European Central Bank policymakers have emphasized that while regional inflation is heavily driven by geopolitical disruptions and supply-side gas shortages, the depreciation of the euro forces defensive rate hikes that compound domestic economic stagnation. Meanwhile, Asian export hubs have ramped up bilateral currency swap frameworks and local-currency settlement mechanisms to hedge against volatility stemming from US federal rate cycles.
Strategic Outlook & Future Scenarios
The trajectory of global financial stability over the coming quarters hinges on the US Federal Reserve's tolerance for international collateral damage versus domestic price containment. If future monthly data reflects sticky service-sector inflation, terminal interest rates could surpass baseline expectations, triggering broader debt distress across vulnerable frontier markets.
Upcoming multilateral gatherings, including G20 ministerial meetings and global trade forums, are poised to become arenas of diplomatic contestation over currency values and capital flow management. Furthermore, elevated domestic political polarization following the midterm elections could constrain Washington's ability to deploy fiscal support packages, leaving the global macro environment heavily vulnerable to monetary policy shocks and subsequent contractions in worldwide commercial demand.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.