G20 Finance Chiefs Convene in Thailand Amid Surging Energy Shock and Iran Escalation
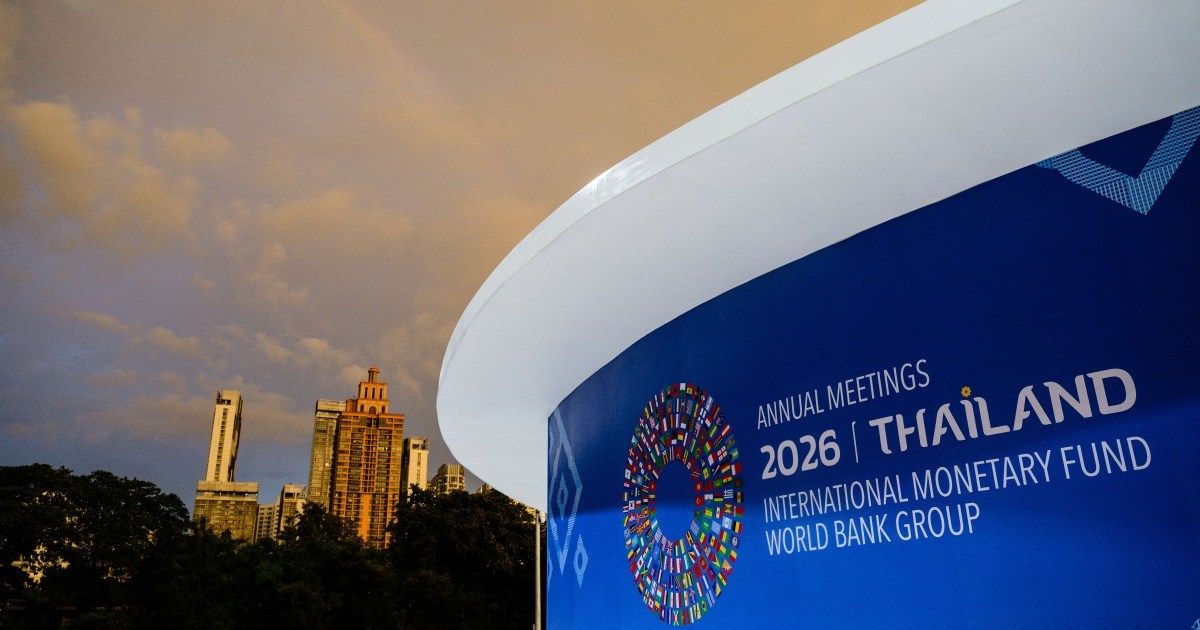
Finance chiefs from the Group of Twenty nations gathered in Thailand to assess compounding economic headwinds as expanding conflict involving Iran disrupts global energy supply chains and complicates monetary policy paths worldwide.
Geopolitical & Core Developments
Finance ministers and central bank governors representing the Group of Twenty (G20) economies have convened in Thailand for high-stakes deliberations overshadowed by escalating military confrontations involving Iran. The summit takes place against the backdrop of expanding hostilities across the Middle East, a theatre that controls pivotal choke points for global petroleum and refined fuel trade. Diplomatic representatives from Washington, Brussels, Beijing, and regional powers face the complex task of navigating geopolitical fractures while seeking common ground on global financial stability.
Over the past seventy-two hours, hostilities have broadened to threaten critical commercial infrastructure across the Persian Gulf, raising concerns of prolonged disruptions to maritime commerce. Western delegations, led by the United States and European allies, have utilized the summit corridors to advance coordinated enforcement of economic sanctions and maritime defense mechanisms. Concurrently, major emerging market representatives, including China, India, and Brazil, have cautioned against unilateral punitive measures, emphasizing that diplomatic containment and de-escalation are vital to shielding developing economies from systemic external price shocks.
Global Trade & Economic Ripples
The immediate consequence of the regional standoff has manifested across global commodity bourses. Brent crude benchmarks and West Texas Intermediate have both registered sharp upside volatility, trading at elevated risk premiums as tankers recalibrate navigation paths away from contested waters. Heightened risk assessments have caused marine war-risk insurance premiums to surge, directly impacting vessel chartering costs across the Arabian Sea and the Persian Gulf. Freight forwarders are increasingly factoring in extended transit durations around the Cape of Good Hope, a costly alternative that strains dry-bulk and container ship capacity.
For central banks, this renewed energy shock revives the specter of imported inflation just as monetary tightening cycles were projected to ease. Importers across South and Southeast Asia, highly dependent on Middle Eastern crude and liquefied natural gas, face rapid currency depreciation pressures against a strengthening U.S. dollar. The ripple effect extends directly into agricultural inputs, as elevated natural gas and hydrocarbon feedstock valuations threaten to elevate global fertilizer prices, injecting fresh volatility into food supply chains across vulnerable import-dependent economies.
Related Intelligence: UNDP Warns of Worsening Global Poverty Amid Escalating Middle East Conflict
International Reactions & Diplomatic Stances
Multilateral financial institutions have issued stark warnings regarding the vulnerability of global growth projections. International Monetary Fund leadership signaled that sustained disruptions in energy markets could force downward revisions to global gross domestic product forecasts for the forthcoming fiscal year, disproportionately impacting low- and middle-income nations burdened by sovereign debt.
Delegates from the host nation, Thailand, alongside Association of Southeast Asian Nations observers, emphasized the necessity of maintaining open shipping corridors and stabilizing energy supply lines to prevent regional industrial slowdowns. United States Treasury officials underscored the requirement for rigorous compliance mechanisms against illicit crude flows, while Beijing's representatives reiterated that dialogue and the restoration of regional security architectures remain the only viable pathway to market equilibrium.
Strategic Outlook & Future Scenarios
In the near term, the trajectory of global financial markets will hinge on whether kinetic actions spill over directly into critical energy-exporting infrastructure or formal maritime transit blockades. Market participants are monitoring the forthcoming Communiqué from the G20 working groups to gauge whether central banks will adopt a coordinated stance on foreign exchange intervention or tactical liquidity provisions to counter commodity volatility.
If tensions remain localized without direct disruptions to throughput via the Strait of Hormuz, energy markets may absorb the geopolitical risk premium through managed inventory drawdowns and spare capacity utilization. Conversely, any sustained closure of key transit corridors or structural damage to upstream production facilities will precipitate persistent supply deficits, obliging monetary authorities worldwide to defer projected interest rate cuts and confront an acute phase of cost-push stagflation throughout the remainder of the calendar year.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.