US Inflation Surges to 3.7 Percent Amid Global Energy Volatility
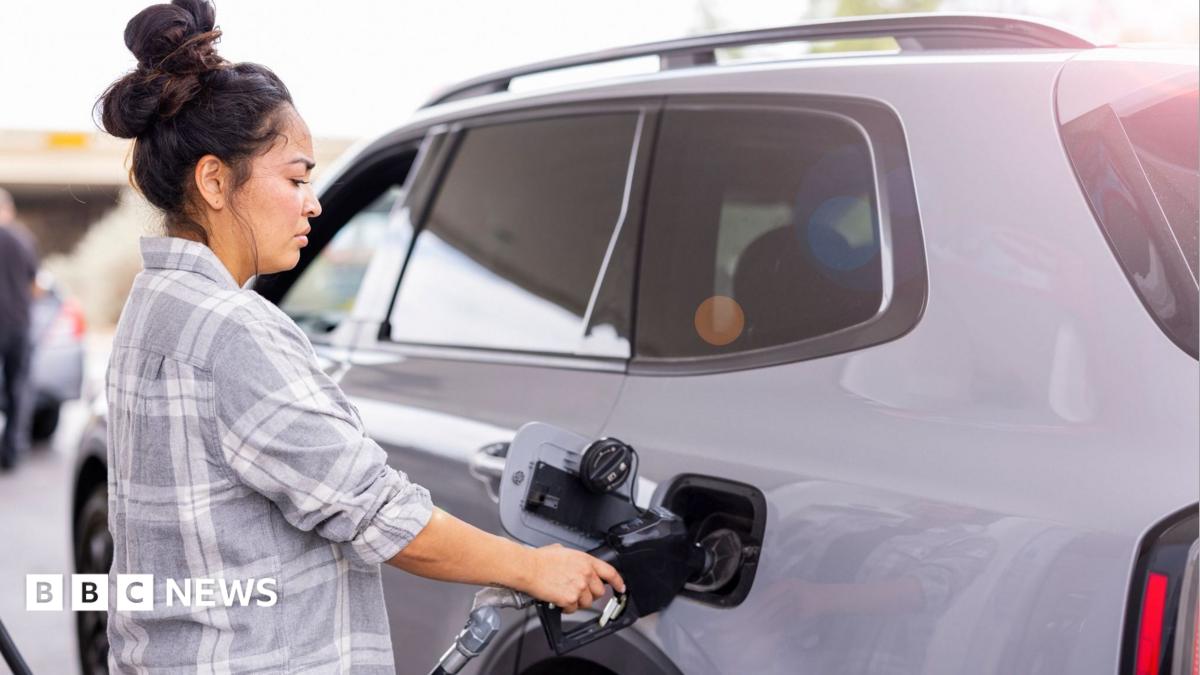
US annual inflation accelerated to 3.7 percent in September driven by surging retail fuel costs. The increase pressures the Federal Reserve to prolong higher interest rates, shaking international currency and commodity markets.
Geopolitical & Core Developments
The United States Department of Labor revealed that headline consumer inflation advanced to an annualized rate of 3.7 percent through September, exceeding consensus expectations and complicating domestic economic governance on the eve of critical midterm electoral contests. The primary impetus behind the acceleration remains the sharp resurgence in motor fuel costs and refined petroleum derivatives. Crude benchmarks experienced renewed upward pressure following sustained structural interventions across the global oil complex, primarily anchored by coordinated supply curtailments implemented by the OPEC+ coalition.
Washington faces a complex strategic landscape as energy policy intersects directly with macroeconomic stability. The Biden administration's historic releases from the Strategic Petroleum Reserve throughout prior quarters have established lower buffer thresholds, curtailing executive discretion to counter sustained supply friction. Meanwhile, sovereign decisions by key hydrocarbon exporters to prolong output restraint have effectively transferred pricing power back to primary producer states. The convergence of domestic consumer discontent, legislative scrutiny, and external supply decisions highlights how deeply intertwined US monetary indicators have become with international geopolitical maneuvering.
Global Trade & Economic Ripples
The ripple effects of accelerated US inflation are immediately apparent across international financial and mercantile architecture. A recalibration of expectations surrounding the Federal Reserve's policy trajectory has renewed capital flight toward safe-haven US dollar assets. The resultant dollar appreciation elevates the cost of sovereign debt service and critical imports for emerging markets, particularly developing nations dependent on imported food staples and refined fuels invoiced exclusively in greenbacks.
Global energy markets remain under acute physical and financial strain. Elevated pump prices in North America mirror tight refining spreads across European and Asian trading hubs, where distillate stockpiles remain below historical seasonal medians. Maritime freight operators and logistics conglomerates are passing increased bunker fuel surcharges onto cross-border supply chains, compounding price pressures for manufactured goods and consumer merchandise. Concurrently, agricultural producers face heightened input expenditures, as fuel and nitrogen-based fertilizer prices maintain an elevated baseline, dampening margin outlooks across export-oriented economies.
Related Intelligence: Russian Strikes on Kyiv Escalate Black Sea and Energy Market Volatility
International Reactions & Diplomatic Stances
The release has prompted immediate responses across global capitals and multilateral financial institutions. The International Monetary Fund underscored the structural risk of premature policy loosening, warning that entrenched inflationary expectations require central banks in advanced economies to maintain restrictive monetary stances even at the expense of sovereign growth trajectories.
European Central Bank officials noted that imported inflation via elevated dollar-denominated fuel prices constrains European monetary maneuvering, despite flagging industrial productivity across Germany and peripheral manufacturing corridors. In Tokyo and Seoul, finance ministries reaffirmed heightened vigilance against excessive foreign exchange volatility, as widened yield differentials between North American debt instruments and Asian sovereign bonds continue to weaken local currencies. Market analysts from major credit institutions observed that the persistent resilience of US core indicators proves that the final phase of disinflation will require prolonged demand suppression rather than localized supply-side adjustments.
Strategic Outlook & Future Scenarios
Looking ahead, global trade networks must navigate a prolonged period of elevated interest rates and geopolitical uncertainty. The Federal Open Market Committee is widely anticipated to signal that borrowing costs will remain higher for an extended duration, limiting liquidity across global sovereign debt markets. This environment elevates credit default risks for frontier economies currently negotiating debt restructuring frameworks under G20 mechanisms.
Geopolitical escalation points in key maritime choke points, including the Strait of Hormuz and the Bab el-Mandeb, represent ongoing vulnerabilities capable of introducing acute supply shocks to crude transport. Should refined product bottlenecks persist into the winter heating season, major consumer nations may explore secondary retaliatory legislative mechanisms or selective sanctions waivers to induce product flows. In the absence of substantial global supply expansions, structural inflation will continue to dictate international trade balances, sovereign monetary autonomy, and bilateral diplomatic discourse through the coming fiscal year.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.