Iran Regional Leverage Tests Fragile Gulf Détente and Energy Security
Tehran’s aggressive regional posture threatens its diplomatic détente with Gulf neighbors, raising commercial shipping risks and complicating energy security across crucial Middle Eastern transit corridors.
Geopolitical & Core Developments
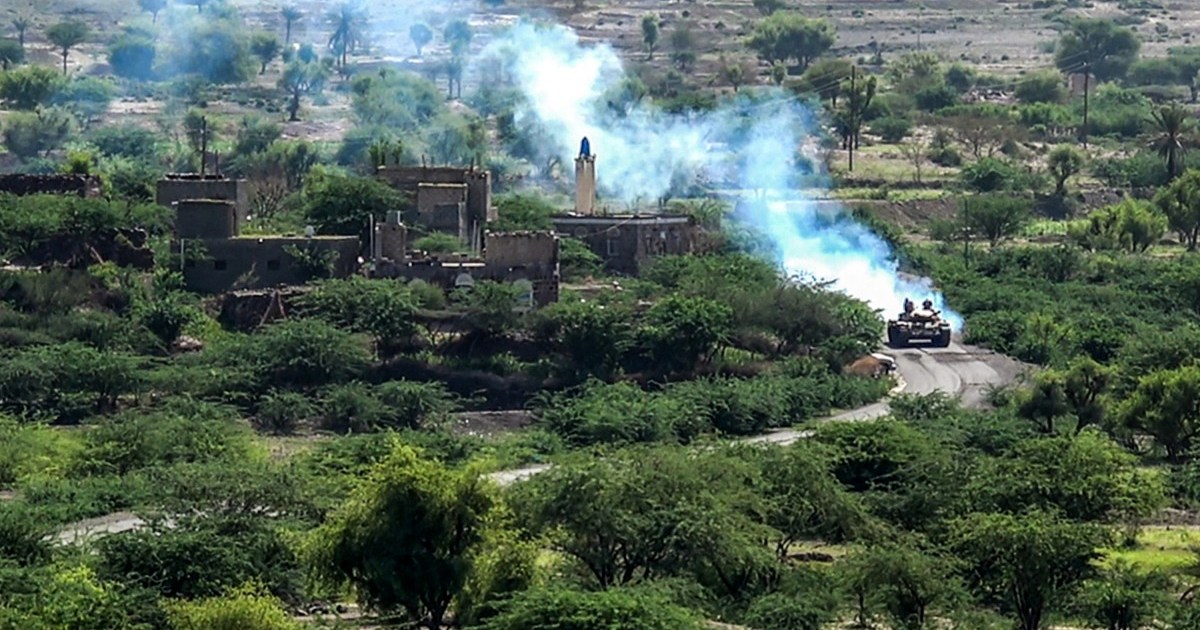
The fragile diplomatic rapprochement established between the Islamic Republic of Iran and the Gulf Cooperation Council (GCC)—most notably Saudi Arabia and the United Arab Emirates—is entering a perilous phase. The détente, brokered under Chinese auspices in Beijing in March 2023, was designed to lower regional volatility, restore formal bilateral ties, and pave the way for cross-border stability. However, Tehran's continued reliance on asymmetric regional leverage, exercised through its aligned network across Yemen, Iraq, Syria, and Lebanon, has reintroduced acute strategic friction.
While Tehran views its forward-defense posture and regional partners as indispensable deterrence mechanisms against Israel and the United States, Gulf capitals perceive these armed non-state actors as direct threats to their sovereign security and economic development. Riyadh and Abu Dhabi have prioritized national transformation blueprints, such as Saudi Arabia's Vision 2030, which demand sustained stability, foreign investment, and unhindered commerce. The escalation of Houthi maritime interdictions in the Bab el-Mandeb strait has laid bare the contradiction between Iran's regional military posture and its diplomatic commitments to its neighbors.
Global Trade & Economic Ripples
The widening breach between Iran's geopolitical maneuvers and Gulf stability carries severe repercussions for international commerce. The Bab el-Mandeb strait and the Strait of Hormuz represent the world's most critical maritime choke points, through which roughly thirty percent of global container shipping and one-fifth of global petroleum liquids transit. Escalating maritime security threats have forced major container liners and tanker operators to bypass the Suez Canal, rerouting vessels around the Cape of Good Hope.
This strategic diversion adds ten to fourteen days to voyages between Asia and Europe, driving up bunker fuel consumption, absorbing vessel capacity, and elevating maritime war-risk insurance premiums. For global energy markets, the structural threat to Gulf export corridors sustains an underlying geopolitical risk premium on Brent crude and liquefied natural gas (LNG) benchmarks. Beyond hydrocarbons, the disruption has destabilized international fertilizer distribution, petrochemical feedstocks, and industrial supply chains, generating persistent cost pressures for import-reliant economies across Europe, Africa, and Asia.
Related Intelligence: New Mexico Equine Incident Highlights Urban Security and Logistics Vulnerabilities
International Reactions & Diplomatic Stances
International responses reflect a fragmented multilateral landscape struggling to manage Middle Eastern volatility. Gulf capitals have maintained a calibrated posture of diplomatic hedging. While expressing serious concern regarding Iranian-backed escalations, Riyadh and Abu Dhabi have refrained from participating directly in Western-led kinetic strikes, seeking to avoid retaliatory proxy attacks on domestic infrastructure. Instead, Gulf diplomats have used direct bilateral channels to warn Tehran that regional economic integration cannot advance alongside maritime intimidation.
In Washington, policymakers have intensified targeted secondary sanctions against illicit financial networks, front companies, and vessel fleets facilitating Iranian petroleum exports. Concurrently, the United Nations Security Council has repeatedly affirmed the necessity of safeguarding freedom of navigation under international maritime law. Meanwhile, Beijing—acting as the primary buyer of Iranian crude and a strategic trade partner to the GCC—has engaged in cautious diplomacy, urging Tehran to ensure that critical commercial sea lanes remain open and secure.
Strategic Outlook & Future Scenarios
The durability of the Iran-GCC normalization framework depends on whether Tehran is prepared to restrain its regional leverage in exchange for long-term economic engagement. If proxy disruptions continue to threaten Gulf maritime routes and infrastructure, GCC members will likely deepen defense and intelligence alignments with Western partners, halting planned cross-border investment initiatives.
Market observers anticipate two primary trajectories over the medium term. Under a managed containment scenario, sustained diplomatic backchannels preserve baseline relations between Riyadh and Tehran, preventing direct state-to-state conflict despite ongoing proxy skirmishes. Alternatively, an escalatory rupture—triggered by a severe incident affecting Gulf critical infrastructure or commercial transit in the Strait of Hormuz—would likely precipitate broader military retaliation and a full reimposition of multilateral sanctions. For commodity traders and logistics operators, elevated risk premiums and strategic hedging will remain essential across Gulf trade corridors for the foreseeable future.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.