India's Equity Markets Stumble Despite Robust Economic Growth
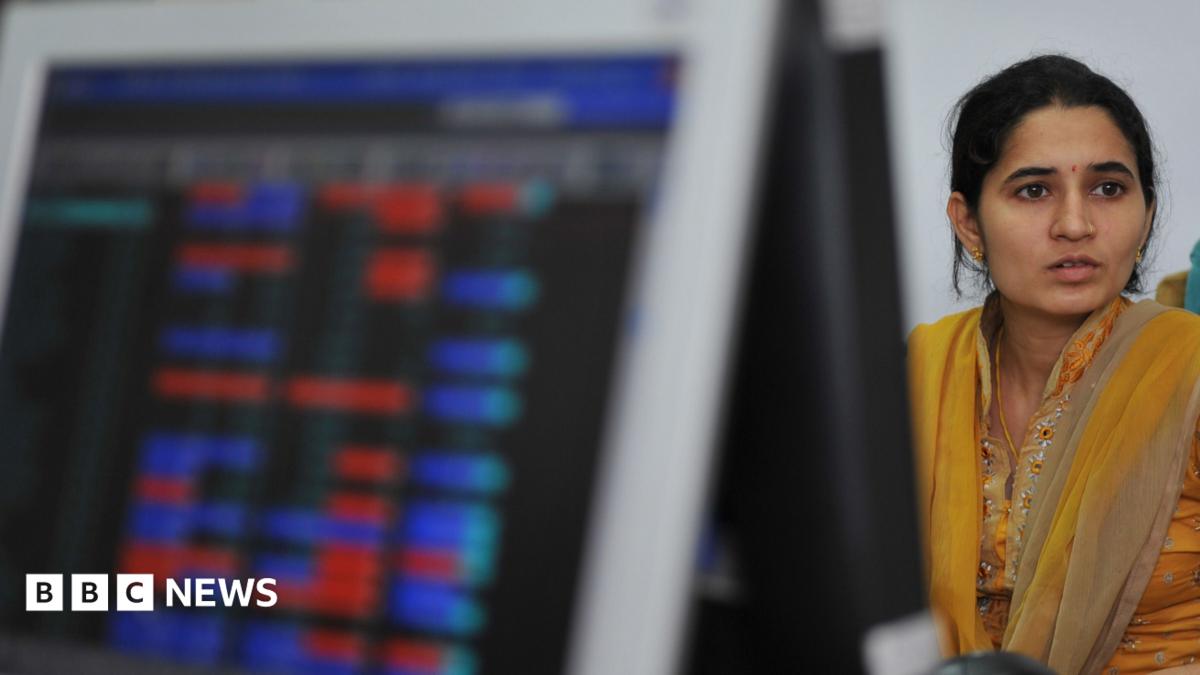
Despite maintaining status as the world's fastest-growing major economy, India's equity markets are experiencing a severe downturn driven by capital outflows, rich valuations, and cooling corporate earnings.
Geopolitical & Core Developments
India has long projected an image of unstoppable economic momentum, frequently citing its status as the world's fastest-growing major economy. Yet, beneath the macroeconomic headlines of robust gross domestic product expansion, a paradoxical crisis has unfolded within the nation's financial architecture. Throughout 2026, Indian equity markets have registered among the worst performances globally, baffling institutional investors and domestic policymakers alike. This divergence between Main Street and Dalal Street stems from a complex convergence of structural pressures, domestic policy adjustments, and shifting global liquidity paradigms.
At the heart of the downturn is an acute reversal of foreign portfolio investments. Global funds, which previously treated Indian equities as a premier growth destination amid Chinese economic uncertainty, have aggressively pulled capital out. This capital flight has been accelerated by tightening domestic monetary conditions, regulatory interventions aimed at curbing speculative retail trading in derivatives, and a persistent contraction in corporate profit margins. State actors and central bank officials have attempted to reassure markets through liquidity injections, but fundamental structural headwinds continue to weigh heavily on investor sentiment across key sectors.
Global Trade & Economic Ripples
As a linchpin of South Asian trade and a critical alternative manufacturing hub, India's market volatility carries profound implications for global commodity markets and international trade supply chains. The sudden contraction in equity valuations has reverberated through foreign exchange markets, placing downward pressure on the Indian rupee and increasing import costs for essential energy commodities. Given India's heavy reliance on imported crude oil and liquefied natural gas, currency depreciation directly exacerbates domestic inflationary pressures, complicating the central bank's monetary policy calculus.
Furthermore, the capital market slowdown threatens to impede foreign direct investment inflows necessary for capital-intensive infrastructure projects under the government's industrial corridors. International shipping lanes, maritime logistics providers, and global industrial conglomerates that rely on Indian manufacturing output are monitoring the financial squeeze closely. Any prolonged deceleration in domestic capital formation risks delaying key capacity expansions, altering regional trade balances, and shifting competitive advantages across emerging Asian markets.
Related Intelligence: US Midterms Loom as Referendum on Trade and Global Policy
International Reactions & Diplomatic Stances
Multilateral institutions, including the International Monetary Fund and the World Bank, have acknowledged the resilience of India's broader economy while highlighting vulnerabilities in its financial sector valuations. Global investment banks have issued cautious notes, downgrading Indian equities from overweight to neutral or underweight positions as risk-adjusted returns deteriorate relative to regional competitors.
Diplomatic and financial analysts suggest that the market correction, while painful for short-term investors, may ultimately serve as a necessary cleansing mechanism to purge excessive speculative froth. Foreign ministry officials and trade attachés from major Western and Asian economies view the volatility as a temporary recalibration rather than a structural decoupling from India's long-term developmental trajectory. Nonetheless, international rating agencies have underscored the critical need for continued fiscal consolidation and transparent regulatory oversight to restore foreign investor confidence.
Strategic Outlook & Future Scenarios
Looking ahead, the trajectory of Indian equities will depend heavily on upcoming corporate earnings reports and the central bank's monetary stance during the upcoming fiscal quarters. If inflation remains contained and global interest rates begin a synchronized descent, foreign institutional capital may gradually return to domestic markets. However, persistent geopolitical risks, volatile energy prices, and heightened trade protectionism could prolong the equity slump.
Upcoming multilateral economic summits and bilateral trade negotiations will serve as crucial barometers for foreign sentiment. Policymakers must balance the imperative of market stability with necessary regulatory reforms to ensure long-term capital market integrity. Failure to address structural equity concerns could divert vital investment flows toward competing emerging markets, fundamentally altering the geopolitical and economic balance of the Indo-Pacific region.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.