IMF Warns Gulf Economies Face Prolonged Slump Amid Regional Conflict
The International Monetary Fund warned that energy-rich Gulf economies will not recover to pre-war growth trajectories in the medium term, dampening fiscal outlooks and raising economic headwinds across South Asia.
The Core Development
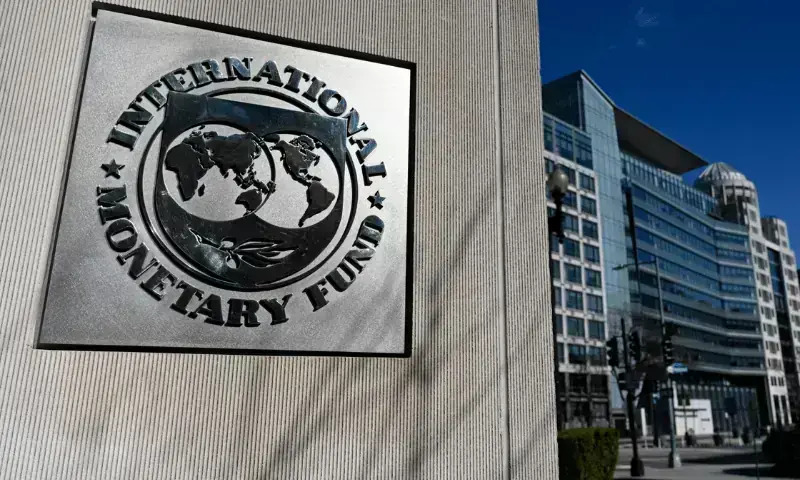
The International Monetary Fund (IMF) has issued a sober evaluation of the Middle East's economic trajectory, warning that energy-rich Gulf economies will not return to pre-war growth rates in the medium term. Speaking to reporters on the sidelines of economic consultations in Bangkok, IMF Regional Director for the Middle East and Central Asia Jihad Azour underscored that the ongoing armed confrontations—expanding beyond Iran to engulf Saudi Arabia and Yemen's Houthi movement—have caused lasting structural damage to regional commerce and maritime infrastructure.
According to the fund's assessment, prolonged conflict across critical shipping lanes has disrupted key maritime transit routes, inflating insurance premiums and curtailing normal supply chain operations. The IMF highlighted that the widespread contraction anticipated across the Gulf Cooperation Council (GCC) member states is driven by infrastructure impairment, heightened regional geopolitical risk premia, and the necessity to divert substantial state revenues toward emergency security and structural resilience rather than direct growth-generating investments.
Commercial & Economic Implications
For Pakistan's domestic economy, the prospect of a stagnant Gulf macro-environment introduces significant vulnerabilities. The GCC states, notably Saudi Arabia and the United Arab Emirates, serve as the primary sources of overseas foreign remittances, which consistently offset Pakistan's perennial trade deficit. A sustained economic slowdown in the Gulf threatens employment generation and wage growth for millions of expatriate Pakistani workers, directly placing pressure on domestic household consumption, retail trade volumes, and consumer liquidity.
Furthermore, supply disruptions along Red Sea and Persian Gulf maritime routes have pushed global freight rates significantly higher. For Pakistani importers, wholesale distributors, and retail businesses, higher marine transport costs translate directly into elevated landed costs for petrochemicals, raw plastics, fertilizer inputs, and imported edible oils. This cost-push inflation is likely to sustain pressure on headline inflation metrics, complicating the State Bank of Pakistan's monetary easing trajectory and maintaining tight operating margins across domestic manufacturing and distribution sectors.
Related Intelligence: G20 Finance Chiefs Convene in Thailand Amid Surging Energy Shock and Iran Escalation
Stakeholder Perspectives & Market Reactions
Financial analysts and trade associations across South Asia have responded to the IMF's pronouncements with concern. The Federation of Pakistan Chambers of Commerce and Industry (FPCCI) and regional merchant bodies have noted that any reduction in Gulf government expenditures will dampen demand for Pakistani textile, rice, and perishable exports destined for Middle Eastern commercial hubs.
Bilateral balance-of-payments considerations also loom large. Investment analysts point out that Pakistan has heavily relied on bilateral debt rollovers, central bank deposits, and deferred oil payment facilities from Gulf partners to satisfy external financing requirements under its IMF Extended Fund Facility (EFF). If GCC sovereign balance sheets face heightened fiscal strain and redirected capital budgets, diplomatic negotiations for bilateral direct investment and concessional financing facilities could face unprecedented friction.
Forward Outlook & Key Watchpoints
In the coming quarters, market observers must track the operational stability of key maritime chokepoints, particularly the Bab el-Mandeb and the Strait of Hormuz, alongside the fiscal adjustments implemented by Saudi Arabia and regional sovereign wealth funds. Commercial entities engaged in regional trade should expect sustained volatility in bunker fuel prices and maritime container rates.
Over the medium term, Pakistani economic managers must prioritize economic diversification and structural reforms to reduce overreliance on Gulf-centric foreign remittances and sovereign debt rollovers. The trajectory of global crude oil benchmarks and subsequent fiscal deficit adjustments in Riyadh and Abu Dhabi will ultimately dictate the extent of external financial spillover into South Asian emerging markets throughout the fiscal year.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.