Global Met Offices Split Over Historic Severity of Current El Nino
Conflicting analytical frameworks among premier global meteorology agencies highlight the immense strength of the ongoing El Nino, carrying major implications for agricultural trade, supply chains, and commodities across South Asia.
The Core Development
Major international meteorological agencies have arrived at divergent conclusions regarding the historical magnitude of the current El Nino weather phenomenon, creating analytical complexity for commodity forecasters and climate modelers worldwide. Britain's Met Office recently warned that the current El Nino event represents an unprecedented atmospheric shift, potentially marking the most significant cycle observed in over a century. Simultaneously, the Japan Meteorological Agency declared it the strongest event ever recorded in its observation history. In contrast, the United States National Oceanic and Atmospheric Administration maintains a more conservative posture, noting that ocean temperature anomalies still trail the peak benchmarks recorded during the historic 1997-1998 and 2015-2016 episodes.
The divergence does not reflect contradictory atmospheric evidence, but rather the structural methodologies each institution deploys to measure oceanic warming. While some meteorological services prioritize broader multi-month thermal averages across the central-eastern equatorial Pacific, others calculate real-time anomalies concentrated in specific maritime zones such as Nino 3.4. As University of Miami climate scientist Emily Becker noted, definitive categorization will only be attainable once the cycle officially concludes, allowing researchers to contextualize its overall energetic footprint against historical records.
Commercial & Economic Implications
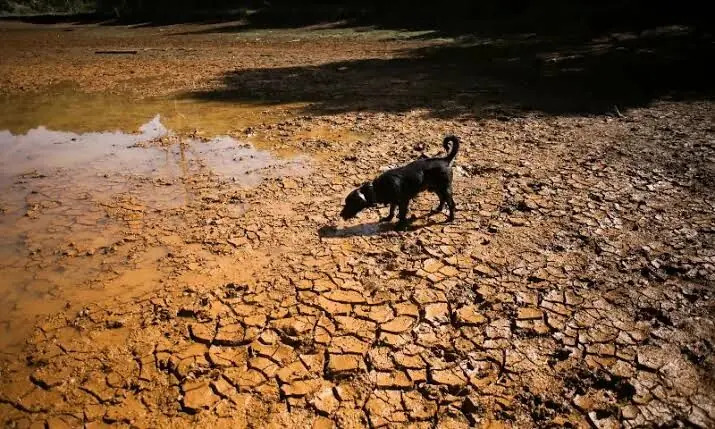
For Pakistan's wholesale and retail economies, the debate over El Nino's exact rank is less critical than its undeniable real-world strength. El Nino events characteristically disrupt monsoon regimes and destabilize precipitation patterns across South Asia. In Pakistan, anomalous climate activity threatens major seasonal harvests, including wheat, cotton, rice, and sugarcane, directly impinging upon domestic agricultural output.
Disruptions in agricultural production swiftly cascade through domestic supply chains, fueling wholesale food inflation and narrowing gross margins for distributors. Volatile rainfall patterns risk depressing cotton yields, imposing severe downstream input shortages on the domestic textile sector, the backbone of Pakistan's export earnings. Concurrently, volatility in global grain and edible oil markets, stoked by unpredictable yields in major producing nations across Southeast Asia and the Americas, exposes Pakistani importers to volatile landed costs. Retailers must manage fluctuating shelf prices amid already constrained consumer purchasing power.
Related Intelligence: US Synthetic Opioid Epidemic Fuels Transnational Supply Chain Tensions
Stakeholder Perspectives & Market Reactions
Domestic agricultural and commercial bodies are monitoring international meteorological outputs with intense scrutiny. Commodity trade associations in Karachi and Lahore emphasize that erratic weather models create severe procurement bottlenecks. Market intermediaries, wary of sudden supply contractions, have increasingly exercised caution, shortening procurement cycles and maintaining leaner inventory reserves to mitigate price risk.
Agronomists and economic planners note that disparate global forecasts present significant policy hurdles. Provincial irrigation authorities require precise precipitation models to manage reservoir levels at Tarbela and Mangla dams effectively. Without consensus on the trajectory of oceanic temperature disruptions, water-release strategies become inherently riskier, complicating irrigation schedules for cash crops during critical germination windows. Industrial bodies continue to lobby federal authorities for robust contingency grain reserves to preempt local spot-market hoarding.
Forward Outlook & Key Watchpoints
Over the next two quarters, commercial market participants must track the transition phase between the current El Nino peak and its projected decay, alongside the potential emergence of a reciprocal La Nina cycle later this year. Rapid shifts between these extremes historically amplify weather volatility, elevating the risk of concentrated unseasonal precipitation or sudden thermal spikes during harvesting phases.
Key watchpoints for Pakistani businesses include the State Bank of Pakistan's food inflation projections, water storage updates from the Indus River System Authority, and import parity pricing on essential agricultural staples. Proactive supply chain management and diversified sourcing strategies will remain vital for retailers and distributors seeking to absorb climate-induced cost shocks.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.