Israel's Political Shift Signals Deepening Geopolitical and Economic Turmoil
Israel's political evolution underscores a deepening security focus following the Gaza conflict, introducing long-term volatility into global commodity and energy markets.
Geopolitical & Core Developments
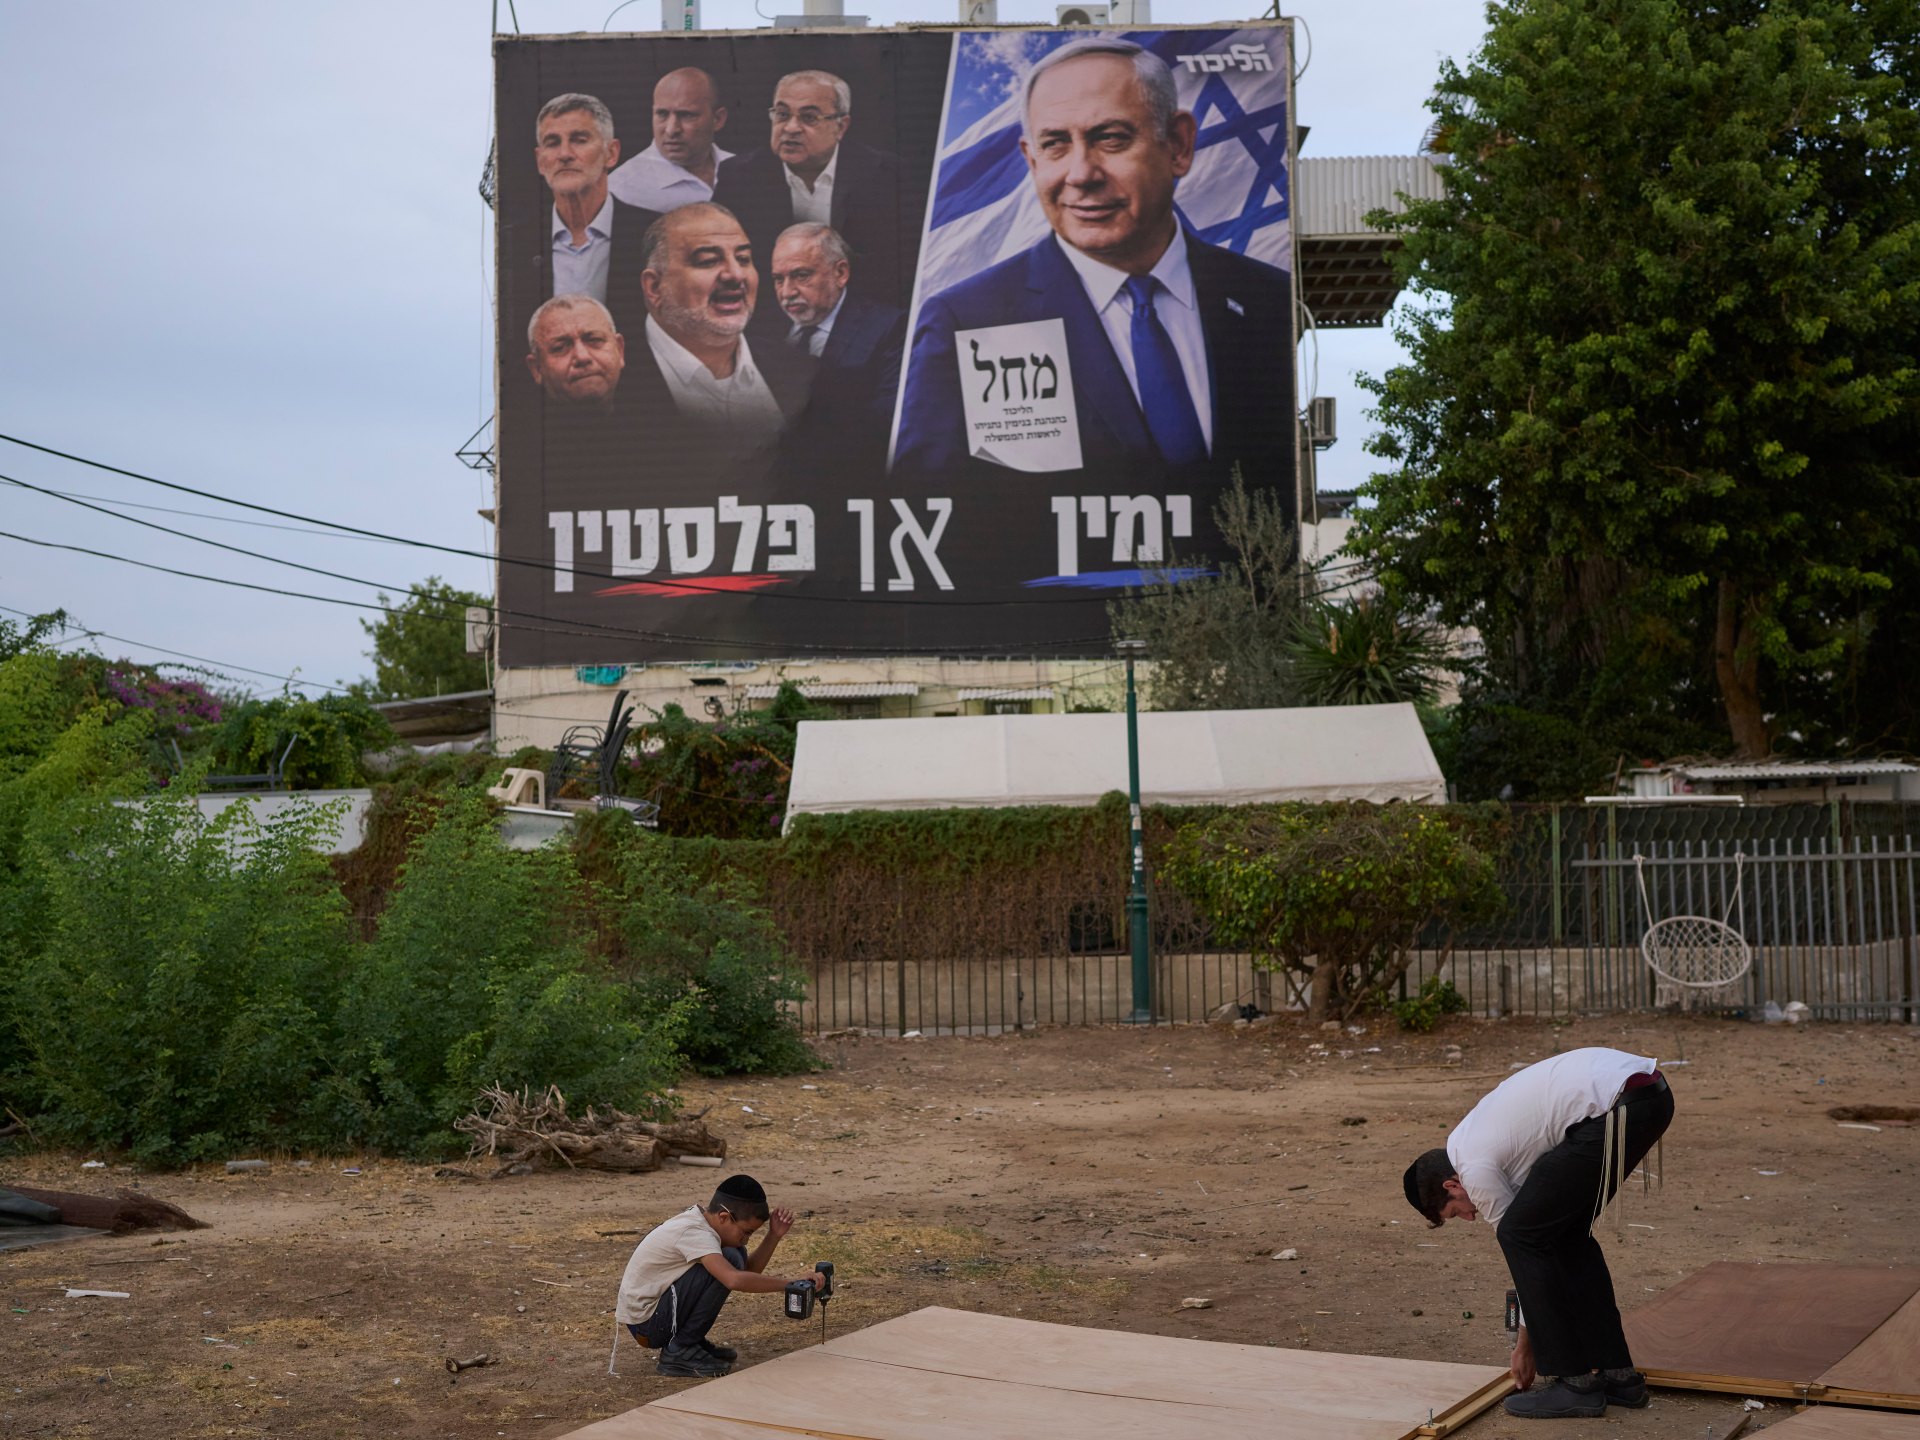
The political landscape within Israel is undergoing a profound structural evolution, signaling not a mandate for moderate reform, but rather a deeper entrenchment of the security-focused nationalism unleashed in the wake of the October 7 events. Domestic political discourse increasingly prioritizes hardline military posture, sidelining diplomatic alternatives and altering the traditional calculus of regional engagement. This domestic hardening reverberates across the wider Middle East, complicating bilateral and multilateral diplomatic frameworks. Regional state actors are forced to recalibrate their strategic alignments, while traditional peace-building architectures face unprecedented strain. State actors in the Levant and the Gulf find themselves navigating a precarious diplomatic tightrope, balancing domestic political pressures with the urgent necessity of regional de-escalation. Strategic stakes have escalated dramatically, as prolonged military campaigns redefine deterrence doctrines and alter long-standing geopolitical boundaries, creating an environment where diplomatic breakthroughs remain exceedingly rare.
Global Trade & Economic Ripples
The persistent regional conflict continues to send shockwaves through global commodity markets, maritime supply chains, and international trade networks. The security situation in critical maritime chokepoints, particularly the Red Sea and surrounding waterways, has forced major container shipping lines to reroute vessels around the Cape of Good Hope. This logistical pivot has substantially increased transit times, inflated freight rates, and added persistent cost pressures to global supply chains. Simultaneously, energy markets remain highly sensitive to any escalation involving major regional producers and transit corridors. Crude oil and natural gas pricing exhibits heightened volatility, driven by trader anxiety over potential supply disruptions in the Persian Gulf and Levant. Currency values across emerging markets are experiencing downward pressure as investors flee to safe-haven assets, while inflationary impulses complicate central bank policy trajectories in major importing economies.
Related Intelligence: Riyadh Airport Strike Escalates Regional Tensions and Threatens Energy Markets
International Reactions & Diplomatic Stances
Multilateral institutions and international bodies have expressed profound concern over the deteriorating humanitarian situation and the wider implications for global stability. The United Nations Security Council remains heavily polarized, with formal resolutions frequently hampered by diplomatic friction among permanent members. Major European capitals and Washington continue to walk a diplomatic tightrope, publicly affirming Israel's security imperatives while privately expressing growing alarm over the lack of a viable post-conflict political strategy. Market analysts and risk-assessment firms have revised their long-term forecasts for the Middle East, incorporating permanent risk premiums into sovereign debt ratings and foreign direct investment projections. Regional powers have intensified backchannel communications, yet public stances remain rigidly defined by domestic political imperatives and strategic competition for regional influence.
Strategic Outlook & Future Scenarios
Looking ahead, the trajectory of the region points toward protracted instability rather than swift resolution. Upcoming international summits and diplomatic forums face immense pressure to deliver credible frameworks for humanitarian relief and economic reconstruction, though expectations remain subdued. Geopolitical escalation points remain numerous, with the risk of miscalculation along northern borders and maritime routes threatening to draw in external powers. For global commerce, businesses must adapt to an operating environment defined by structural uncertainty, elevated shipping costs, and chronic supply chain fragility. The long-term economic toll will likely manifest in subdued growth across the region and sustained risk premiums in international energy markets, necessitating robust risk-mitigation strategies for multinational corporations and commodity traders alike.
Join Our Official WhatsApp Channel
Receive live commodity alerts, policy changes, and commercial intelligence directly on WhatsApp.